Shipowners holding aging tonnage now face compressed timelines for profitable recycling as eased Iran sanctions and resumed Red Sea sailings threaten to reverse the current shortage-driven price spike.
Advertisement
Advertisement
Shipowners holding aging tonnage now face compressed timelines for profitable recycling as eased Iran sanctions and resumed Red Sea sailings threaten to reverse the current shortage-driven price spike.
Owners who have kept older vessels trading because demolition returns were strong now confront a different calculation. With the Suez route reopening, a meaningful portion of the global fleet will require fewer days to complete voyages, reducing the urgency to remove capacity. The same ships that looked like candidates for the beach this year may instead stay in rotation for another twelve to eighteen months. For a 15-year-old Panamax bulker, that extra trading time can erase the narrow margin between a $520 per light-displacement-tonne offer today and the lower levels likely once more units chase fewer berths.
Wirana Shipping’s assessment ties the two developments together. Relief on Iranian sanctions is expected to restore normal oil-trading patterns and free up vessels that have been idling or operating under restrictive flags. Those units, once reintroduced to mainstream employment, will compete directly with older tonnage that owners had earmarked for recycling. The net effect is an increase in active supply at the very moment demand for demolition slots is softening.
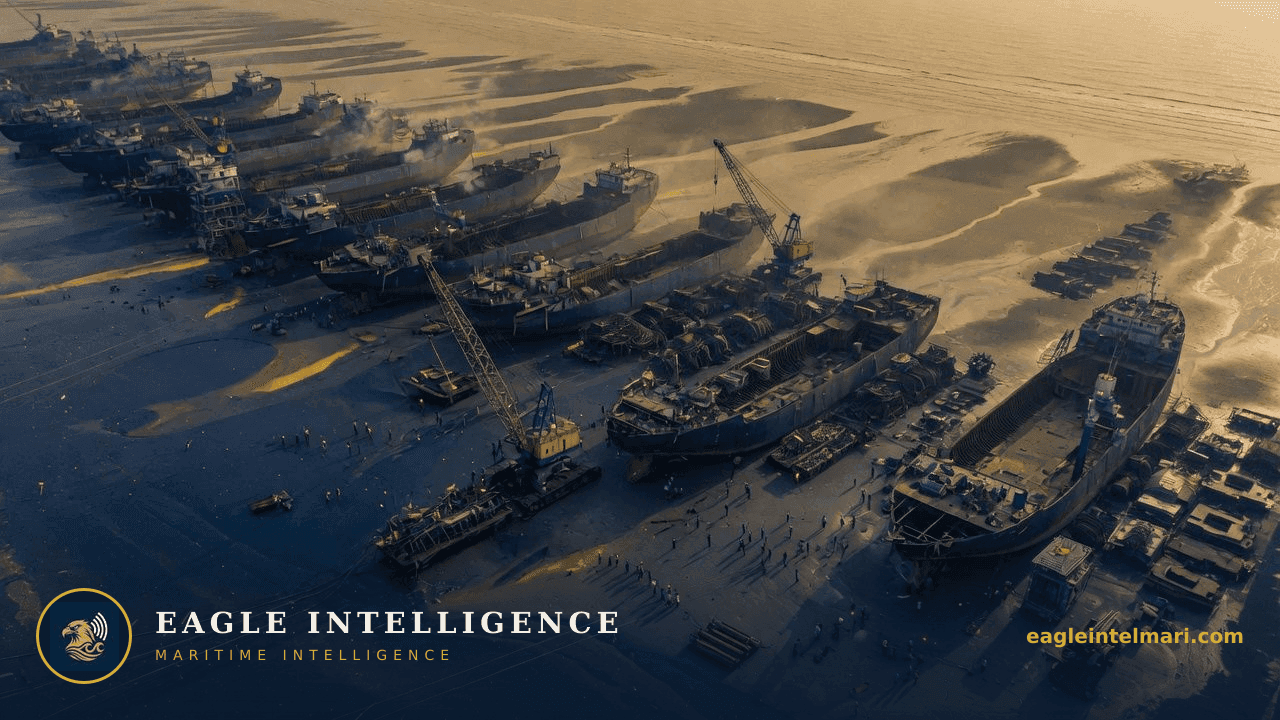
Alang, Chittagong and Gadani have operated near full stretch for the past two years because cash buyers could not secure enough candidates. A sudden increase in available tonnage would flip the dynamic from shortage to surplus. Yards that have invested in expanded plots and higher-capacity beaching facilities may find themselves competing aggressively for work. That competition typically translates into lower purchase prices rather than higher throughput, squeezing margins for the cash buyers who have carried much of the recent volume.
For operators with vessels approaching their twentieth year, the decision window is narrowing. A six-month delay in sending a ship for demolition could mean accepting $80–120 per tonne less once the market corrects. Finance teams and technical managers are therefore being asked to model two residual-value scenarios: one assuming continued Red Sea avoidance and another assuming normalized routing by the fourth quarter of 2026. Banks holding mortgages on these assets will want updated valuations before the next quarter-end reporting cycle.
Insurers are equally attentive. Lower scrap values reduce the incentive for owners to dispose of vessels that may already be carrying deferred maintenance. Clubs have already noted a modest uptick in engine and hull claims on older units kept trading longer than originally planned. If scrap prices fall further, that incentive shifts again, raising the possibility of more vessels reaching the beach in marginal condition and triggering additional environmental or worker-safety liabilities for the recycling states.
Monitor the next round of Iranian crude cargo fixtures and any formal announcement on Red Sea convoy protocols; either development crossing a sustained threshold of ten additional VLCCs or Suezmaxes per month would likely mark the inflection point for demolition prices.
Advertisement
Advertisement
⚠️ Intelligence Disclaimer: This analysis is produced by Eagle Intelligence's AI-assisted automated analysis system and is provided for informational purposes only. See our editorial standards. It is not a substitute for official maritime safety advisories from UKMTO, MSCHOA, IMO, or flag state authorities. Operational decisions should always be based on official guidance and professional judgment. Eagle Intelligence accepts no liability for any loss arising from reliance on this content.
Live chokepoint status, war-risk shifts, and the daily maritime wire, straight to your inbox. Free.
Leave a comment
All comments moderated for quality
