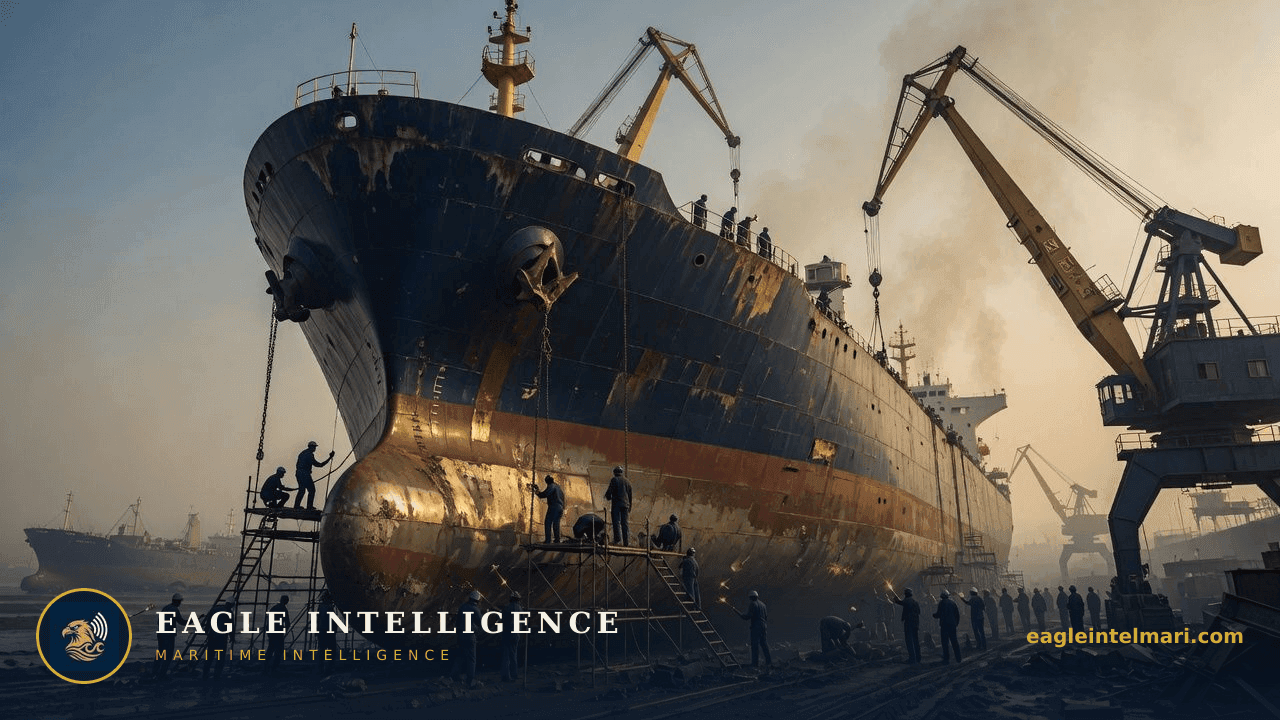
Shipowners holding 15-20 year old tonnage now face softer Indian offers and a wait-and-see stance from cash buyers, delaying fleet renewal decisions until regional tensions ease.
Advertisement
Advertisement
For owners and cash buyers deciding whether to commit older vessels to Indian or Bangladeshi beaches this summer, the immediate signal is lower bids and stalled negotiations after fresh Middle East flare-ups.
Best Oasis reports that sentiment in Alang and other Indian centers has softened, with cash prices falling for tankers, bulkers and containers alike. The correction mirrors weaker steel-plate demand and the caution that follows any spike in regional risk premiums. Yards that were quoting competitive numbers only weeks ago are now widening their discounts rather than chasing volume.
Leading cash buyers have shifted to short-dated letters of intent that can be cancelled if scrap steel futures move another 2-3 percent lower. This protects their margins but leaves owners without firm lay-can windows, pushing potential demolition candidates back into trading or lay-up instead.
Lower scrap values extend the economic life of marginal tonnage by six to twelve months for many owners. That incremental supply arrives just as charterers reassess routes around the Strait of Hormuz, keeping freight rates from rising as quickly as they might otherwise. Charterers gain short-term optionality; owners absorb higher operating costs on vessels that would have been scrapped.
Hull underwriters are already adjusting scrap-value assumptions downward in policies renewed after 1 July. Banks with mortgages on older tonnage face fresh loan-to-value pressure if the Indian market stays depressed into the third quarter. P&I clubs, meanwhile, see fewer green-recycling declarations, keeping their exposure to substandard yards slightly elevated.
A similar pause occurred after the 2019 tanker attacks near the Strait. Demolition volumes from the Indian subcontinent dropped roughly 25 percent quarter-on-quarter before rebounding once tensions eased and steel prices recovered. The current episode follows the same pattern, though today’s larger shadow fleet and tighter ESG scrutiny make a swift rebound less certain.
Monitor weekly Best Oasis and GMS price lists for any sustained recovery above the current corrected levels; a 5 percent uptick would signal that recyclers are ready to re-enter the market and clear the backlog of aged vessels.
Advertisement
Advertisement
⚠️ Intelligence Disclaimer: This analysis is produced by Eagle Intelligence's AI-assisted automated analysis system and is provided for informational purposes only. See our editorial standards. It is not a substitute for official maritime safety advisories from UKMTO, MSCHOA, IMO, or flag state authorities. Operational decisions should always be based on official guidance and professional judgment. Eagle Intelligence accepts no liability for any loss arising from reliance on this content.
Live chokepoint status, war-risk shifts, and the daily maritime wire, straight to your inbox. Free.
Leave a comment
All comments moderated for quality
