A small weekly correction in Indian demolition prices does not signal improving fundamentals; owners should expect continued pressure on end-of-life vessel values through the summer.
Advertisement
Advertisement
Indian breakers trimmed cash offers by roughly $10-15 per light displacement tonne this week, yet the move reflects thin enquiry rather than any shift in underlying steel demand.
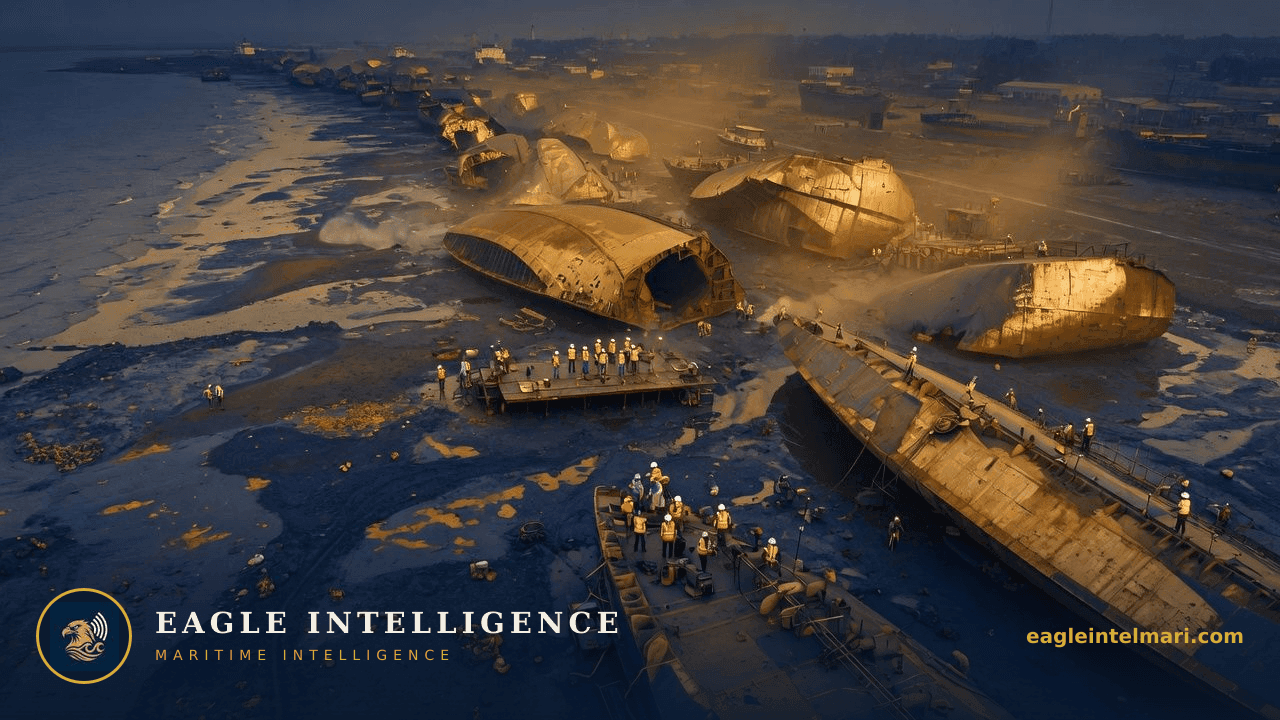
Yards along the Gujarat coast are running at little more than 40 percent utilisation, with only a handful of capesize and suezmax tankers currently under negotiation. The absence of larger units has left many facilities chasing smaller handysize and feeder tonnage, intensifying competition and capping any upside in bids.
Domestic re-rolling mills in Bhavnagar and Mumbai continue to source most feedstock from domestic scrap and imported shredded material rather than shipbreaking. With hot-rolled coil futures on the Multi Commodity Exchange down 4 percent since mid-May, breakers have little incentive to lift their offers to owners.
For tonnage that must be sold before the monsoon season closes Alang’s beaches in late June, the modest correction translates into a $150,000–$250,000 shortfall versus March levels on a typical 15,000 LDT vessel. Charterers with redelivery options in the Indian Ocean are already factoring lower residual values into their calculations when assessing two-year extensions versus prompt sale.
Underwriters have begun to apply modest additional premiums on vessels declared for recycling in South Asia, citing both the environmental risks associated with beaching and the possibility of further price erosion. Several mutuals are now requiring cash deposits equivalent to 15 percent of the sale price before cover is confirmed for the final voyage.
Chittagong and Gadani continue to quote $30–40 below Indian levels, yet stricter import licensing and acute dollar shortages have kept Bangladeshi yards largely out of the market. Should the State Bank of Pakistan ease letters of credit in July, a sudden influx of competitive bids could widen the current correction into a more pronounced slide.
If Chinese steel demand rebounds on fresh stimulus, Indian breakers could regain $20 per tonne within four weeks, stabilising values ahead of the post-monsoon rush. A continuation of the present sideways steel market would keep prices within a $5 band, prompting owners to delay sales until October. Should the rupee weaken beyond 85 to the dollar, breakers would be forced to cut another $15–20 to protect margins, triggering a broader re-pricing across the subcontinent.
Advertisement
Advertisement
⚠️ Intelligence Disclaimer: This analysis is produced by Eagle Intelligence's AI-assisted automated analysis system and is provided for informational purposes only. See our editorial standards. It is not a substitute for official maritime safety advisories from UKMTO, MSCHOA, IMO, or flag state authorities. Operational decisions should always be based on official guidance and professional judgment. Eagle Intelligence accepts no liability for any loss arising from reliance on this content.
Live chokepoint status, war-risk shifts, and the daily maritime wire, straight to your inbox. Free.
Leave a comment
All comments moderated for quality
