
Sanctions
Shadow Fleet Scrapping May Blunt 25% Tanker Order Book Pressure
Pace of sanctioned tanker removals, not just newbuild deliveries, will decide whether rates soften during the Hormuz crisis, operators and BIMCO data indicate.
Eagle IntelligenceDrafted by the Eagle desk system; no individual review recordedRecorded urgency at publication: Medium. Not a live alert.
Advertisement
Advertisement
The rate outlook for crude tankers hinges less on the record 25% order book than on how quickly regulators and owners dismantle the sanctioned shadow fleet amid escalating Hormuz tensions.
Order Book Meets Shadow Fleet Attrition
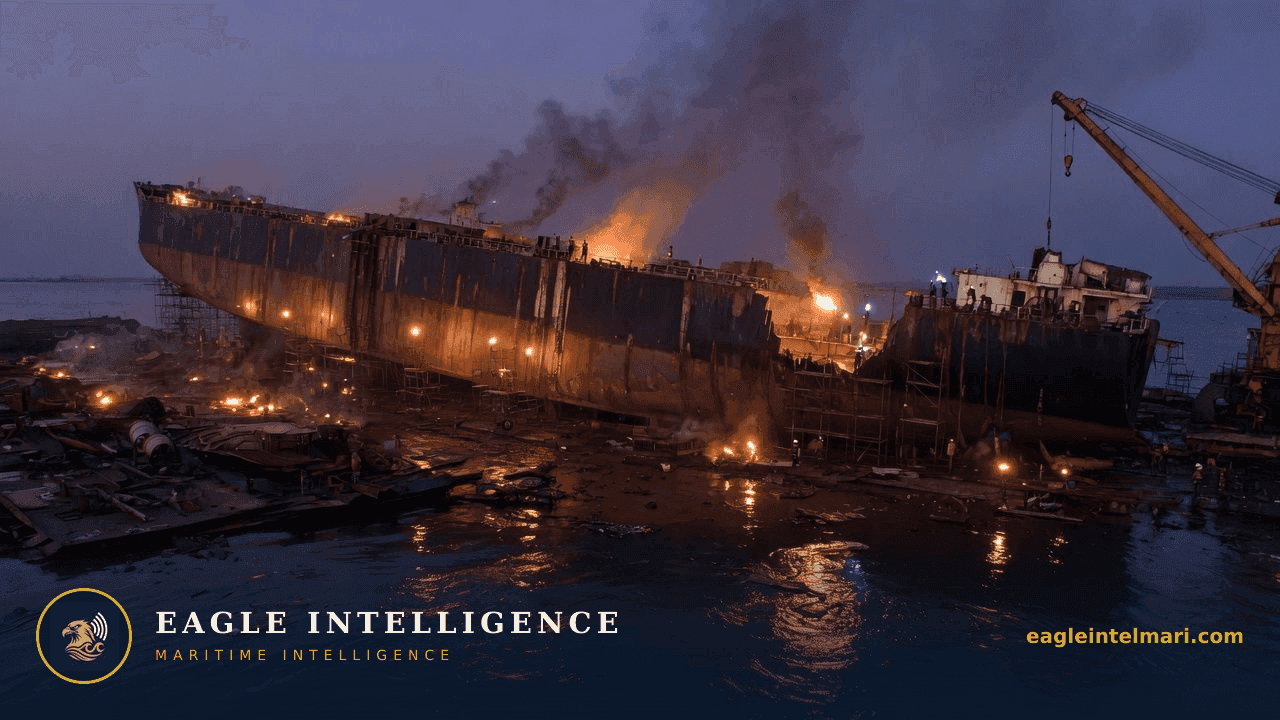
BIMCO’s estimate places the crude tanker order book at nearly one-quarter of the existing fleet, the highest ratio recorded since the 2008 financial crisis. Yet several operators argue this overhang is already being offset by accelerating removals of older, sanctioned tonnage that has been running dark or switching flags to move Iranian and Russian barrels. Each vessel scrapped or permanently idled under sanctions removes roughly 300,000 dwt of capacity that would otherwise compete for legitimate cargoes once newbuilds arrive.
Hormuz Throughput as Demand Swing Factor
The Strait of Hormuz remains the decisive variable. Sustained Iranian threats or kinetic incidents that cut daily tanker transits by even 15% would tighten effective supply faster than any newbuilding wave could loosen it. Charterers already report 20-30 day delays for westbound loadings from the Gulf, pushing some VLCCs into longer-haul routes that absorb tonnage and support rates. Conversely, a quick de-escalation would release pent-up barrels and expose the order-book surplus more quickly.
P&I Clubs and Hull Underwriters Drive Early Removals
Insurers are moving first. Several International Group clubs have quietly withdrawn cover from vessels with repeated AIS gaps or opaque ownership chains, forcing owners to choose between lay-up, reflagging at higher cost, or outright demolition. This insurance squeeze is proving more effective at shrinking the shadow fleet than formal sanctions lists alone, because it raises daily operating costs above breakeven for marginal tonnage.
Owner and Charterer Divergence
Tanker owners with modern eco-ships view the sanctions-driven scrapping wave as a natural fleet-renewal mechanism that protects their asset values. In contrast, charterers reliant on discounted shadow-fleet barrels face higher replacement costs and are lobbying flag states for carve-outs. The split is already visible in fixture data: clean petroleum product traders have shifted more volume to compliant tonnage, while some crude traders continue to absorb the risk premium.
Historical Parallel to 2019-2020 Sanctions Surge
The current dynamic echoes the 2019-2020 period when U.S. sanctions on COSCO and several Chinese operators removed an estimated 4 million dwt of tanker capacity within six months. Rates spiked despite a still-large order book because the removals were front-loaded. Today’s order book is larger, yet the shadow fleet is also bigger, suggesting the net supply effect could again prove neutral or even tightening if scrapping accelerates.
Three Forward Scenarios
A rapid sanctions-enforcement clampdown combined with Hormuz friction lasting into Q4 would likely lift VLCC TCEs above $60,000 per day by year-end. A negotiated Hormuz easement without new sanctions listings would instead allow the order book to weigh on rates by early 2027, pushing older non-sanctioned tonnage into lay-up. The middle path—gradual shadow-fleet attrition with episodic Hormuz incidents—points to range-bound earnings around current levels, with spikes only during discrete transit disruptions.
Advertisement
Advertisement