Ten new ballast water treatment systems ordered for specialist vessels signal sustained European demand for regulatory-compliant tonnage even as offshore markets tighten.
Advertisement
Advertisement
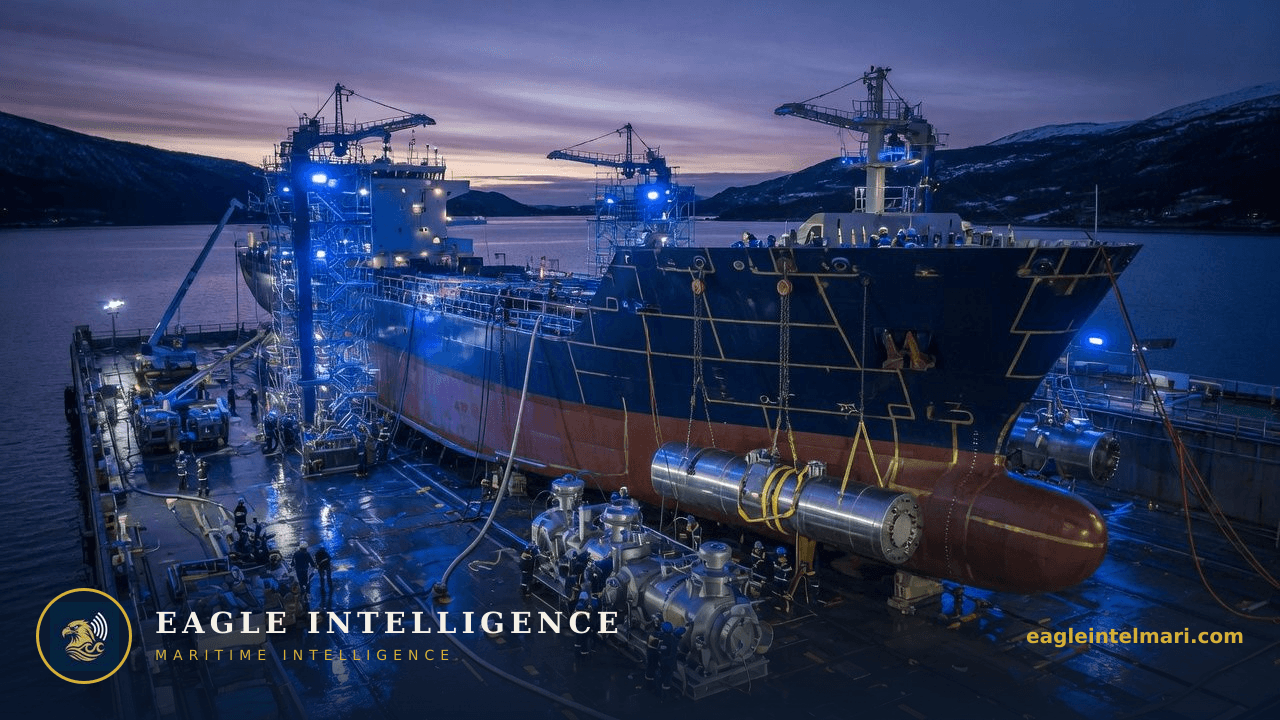
Norwegian Greentech’s latest contract win for ten ballast water treatment systems underscores continued investment in compliant newbuilds across the North Sea and adjacent basins, where offshore support, cable-laying and dive-support vessels are being ordered despite volatile day rates.
The majority of the units are destined for newbuildings rather than retrofits, covering cable layers, dive-support ships, offshore support vessels and live-fish carriers ordered at yards in Norway, Spain and the Netherlands. This distribution reveals a deliberate preference among European owners for embedding treatment technology at the construction stage, avoiding the higher costs and downtime associated with later installations. Each system typically processes 200–2,000 m³/h depending on vessel type, translating into roughly 15,000–20,000 m³ of treated ballast water daily across a full offshore support fleet rotation.
The IMO Ballast Water Management Convention’s D-2 standard remains the binding trigger. With enforcement now universal and Port State Control inspections increasingly rigorous in Rotterdam, Hamburg and Stavanger, owners ordering specialist tonnage see little value in deferring compliance. The contracts coincide with the final wave of existing-ship deadlines that ended in 2024, yet newbuild programmes continue to specify the technology because classification societies and flag states refuse to issue full-term certificates without verified systems. European yards have therefore embedded BWTS selection into the basic design phase, shortening lead times and locking in Norwegian Greentech’s compact electro-chlorination or UV units that fit constrained engine-room layouts typical of cable and dive vessels.
P&I clubs have begun adjusting condition surveys to verify active BWTS operation rather than mere presence. A non-compliant discharge can trigger fines exceeding €50,000 per incident plus clean-up costs that fall outside standard club cover. Hull underwriters, meanwhile, note that properly integrated systems reduce corrosion risk inside ballast tanks compared with older chemical dosing methods. Consequently, owners placing these ten orders are likely to secure modest premium reductions of 3–5 % on new policies, provided they demonstrate crew training records and maintenance logs from delivery.
Specialist vessels present unique challenges: frequent short ballast operations, dynamic positioning and rapid port calls leave limited windows for system maintenance. Norwegian Greentech’s deliveries include remote monitoring modules that transmit performance data to shore teams, allowing superintendents to flag filter fouling or UV-lamp degradation before a PSC detention occurs. For crews on rotation-limited offshore vessels, the added workload is modest but requires targeted familiarisation; failure to log correct procedures has already produced detentions in Spanish and Dutch ports this year.
First, sustained high oil-service activity could accelerate replacement of older tonnage, pushing annual BWTS orders for offshore vessels above 120 units globally by 2027 if day rates remain above $25,000. Second, a prolonged soft market might shift demand toward lower-cost Chinese and Korean systems, eroding Norwegian Greentech’s European share unless it secures further yard frame agreements. Third, any tightening of IMO guidelines on invasive-species sampling frequency would favour systems with real-time biological sensors, an area where the Norwegian supplier already holds patents; early adopters could then command charter premiums from energy majors sensitive to ESG reporting.
Spanish and Dutch builders benefit from proximity to North Sea operators and from EU taxonomy rules that classify compliant vessels as sustainable assets, unlocking green financing. Norwegian yards, already dominant in cable layers, gain an additional differentiator by offering integrated BWTS packages that reduce commissioning time. Should Asian competitors enter this niche with equivalent class approvals, price pressure will intensify, yet delivery reliability and after-sales support remain decisive for owners facing strict charterer vetting on environmental performance.
Advertisement
Advertisement
⚠️ Intelligence Disclaimer: This analysis is produced by Eagle Intelligence's AI-assisted automated analysis system and is provided for informational purposes only. See our editorial standards. It is not a substitute for official maritime safety advisories from UKMTO, MSCHOA, IMO, or flag state authorities. Operational decisions should always be based on official guidance and professional judgment. Eagle Intelligence accepts no liability for any loss arising from reliance on this content.
Live chokepoint status, war-risk shifts, and the daily maritime wire, straight to your inbox. Free.
Leave a comment
All comments moderated for quality
